Florida Homeowners Insurance Claim Denied?

Florida homeowners pay thousands of dollars in insurance premiums each year, trusting that their insurance company will be there to help them when their home is damaged. Unfortunately, Florida insurance companies sometimes incorrectly deny claims, leaving homeowners to fend for themselves and face significant repair costs without the coverage they expected.

Insurance companies may deny claims based on incorrect conclusions about what caused the damage, misinterpretations of the policy, or incomplete investigations. They may also rely on exclusions that do not actually apply to the damage.

Just because your insurance company denied your claim does not mean its decision was correct.

At Schatzman & Hovanyecz, P.A., we have successfully challenged denied homeowners insurance claims and obtained coverage for our clients. If your claim has been denied, we can help determine whether you may be entitled to payment.

Why Do Insurance Companies Wrongfully Deny Homeowners Claims?

Most Florida homeowners insurance policies provide what is known as all-risk coverage for damage to the home. This means that damage to the home is generally covered unless the insurance policy specifically excludes it. If the insurance company denies the claim, it generally has to prove that the damage is excluded under the policy.

This is an important protection for homeowners. Insurance companies cannot simply deny claims by pointing to an exclusion. They must prove that the exclusion applies to the reported damage or cause of loss.
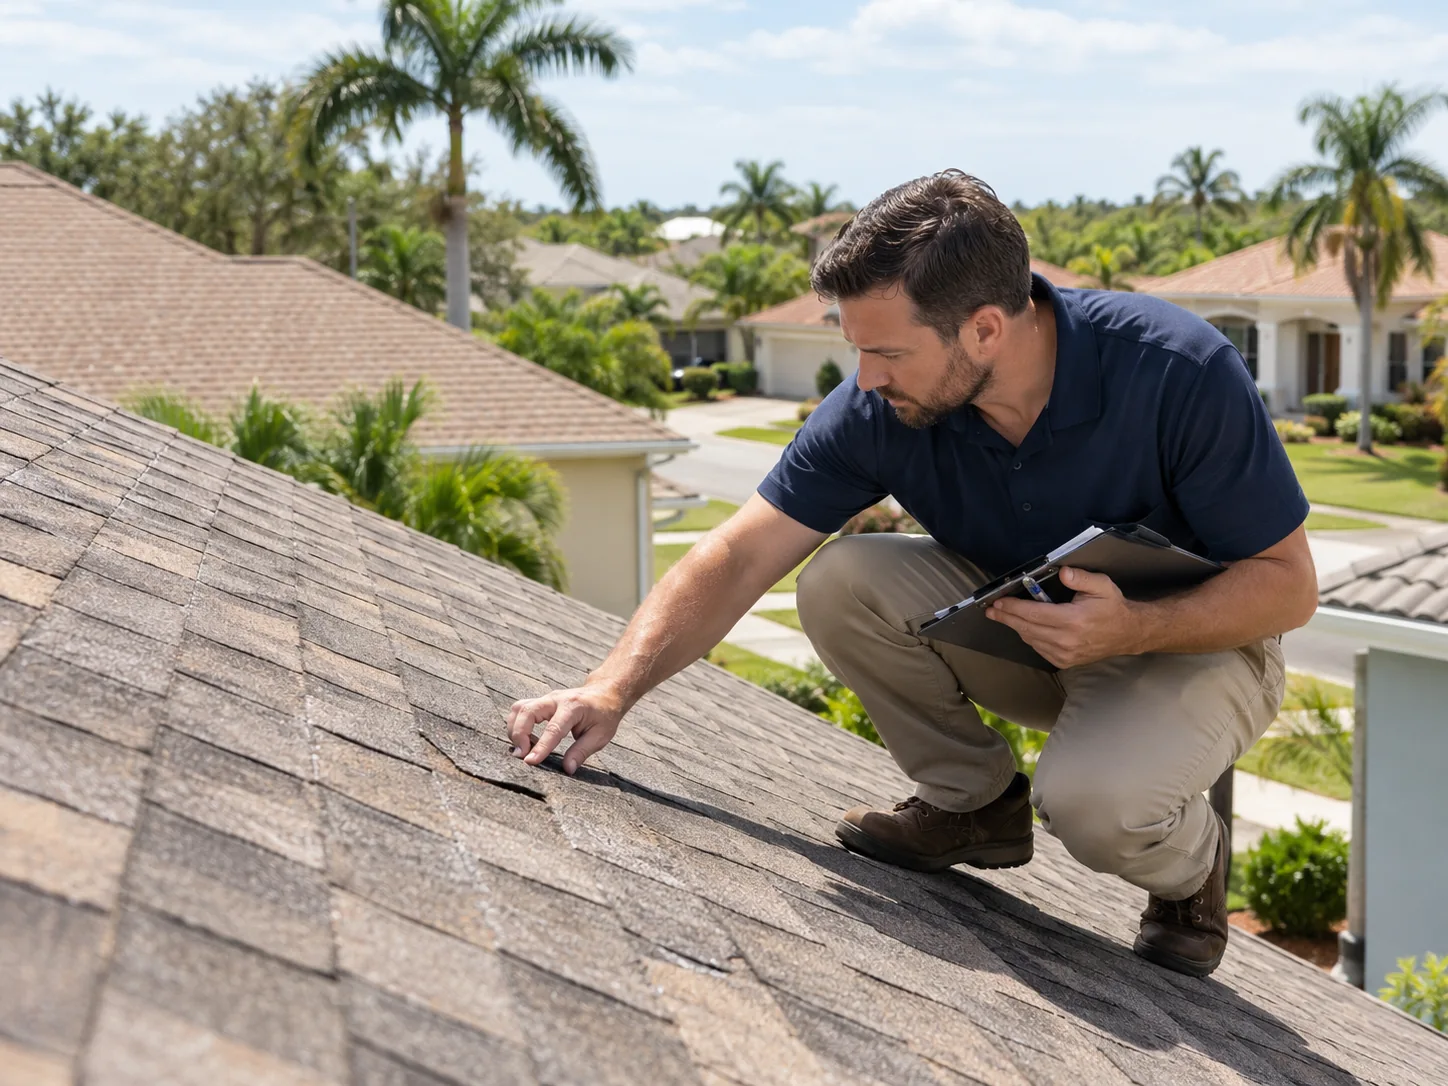
Insurance adjuster inspecting shingles on a Florida home's roof while holding a clipboard

Some of the most common reasons insurance companies give for denying claims, even when coverage may exist, include:

Roof damage blamed on age or wear and tear. Insurance companies frequently deny roof claims by attributing damage to the age of the roof, deterioration, or poor maintenance. However, an older roof can still suffer new damage during a hurricane or severe storm. The existence of prior wear and tear does not automatically mean that new storm damage is excluded from coverage.

Roof damage blamed on prior repairs. Insurance companies may also deny roof claims because the roof was previously repaired or contains patched areas. However, the existence of prior repairs does not automatically mean that new damage is excluded. A roof that has undergone repairs can still sustain new damage from wind or other covered events.

Water damage blamed on long-term leaks. Insurance companies may deny water damage claims because they believe a plumbing leak continued for a long period of time. However, leaks often occur behind walls, beneath flooring, or inside cabinets, where homeowners may not discover them immediately. A homeowner may not discover the leak until water stains, damaged flooring, or other signs of damage become visible. Depending on the policy and circumstances, the resulting water damage may be covered.

Damage blamed on faulty construction or maintenance. An insurer may attribute damage to defective workmanship, improper installation, or a lack of maintenance. Although policies often exclude these causes of damage, the resulting damage may still be covered.

Claims denied because of late reporting. Insurance companies may deny claims because they believe the homeowner waited too long to report the damage. However, the circumstances surrounding the delay and whether it affected the insurer’s ability to investigate may be important in determining whether the denial can be challenged.

Denials involving hidden damage. Some insurers deny claims involving damage that developed out of sight, including concealed water damage and structural deterioration. Yet some insurance policies provide coverage for specific types of resulting damage.

For example, certain policies cover a qualifying collapse caused by hidden termite damage, even though termite damage itself is generally excluded.

Our firm has successfully challenged denials involving hidden termite damage and hidden water damage. Learn more in our article on denied termite damage insurance claims.

You can also read our article on Florida water damage insurance claims for additional information about plumbing leaks and related coverage disputes.

An insurance company’s stated reason for denying a claim does not necessarily justify the denial.

Can a Denied Homeowners Insurance Claim Be Overturned?

Yes. A denied homeowners insurance claim can be overturned, and our firm has successfully obtained insurance coverage for clients whose claims were initially denied.

Some denials are reversed through negotiations or mediation, while others require legal action. A denial letter does not necessarily prevent you from recovering insurance benefits.

At Schatzman & Hovanyecz, P.A., we have experience challenging denials involving hurricane damage, plumbing leaks, policy exclusions, and other disputed losses.

If your claim was denied because of the condition of your roof, prior roof repairs, a plumbing leak, hidden damage, or another disputed issue, our firm may be able to help you obtain the coverage you are entitled to under your insurance policy.

What Should You Do After Your Insurance Claim Is Denied?

If your homeowners insurance claim has been denied, keep the insurance company’s denial letter, take photographs of the damage, and keep any estimates or inspection reports you have received.

It is important not to delay. Florida insurance claims are subject to deadlines, and waiting too long may affect your ability to pursue coverage.

Having an experienced property insurance attorney review your denied claim can help you determine whether the denial should be challenged.

Florida Homeowners Insurance Claim Denied?

At Schatzman & Hovanyecz, P.A., we have successfully overturned insurance claim denials and obtained benefits for homeowners throughout Florida.

If your insurance company has denied your claim, you may still be entitled to payment for your property damage. You do not have to accept the insurance company’s decision without having it reviewed.

Contact our firm today for a free consultation. We can review your denied claim and help you determine whether you can recover the insurance benefits you were denied.
Florida Water Damage Insurance Claims: What Homeowners Need to Know

A leaking pipe, failed appliance, or other water leak may seem like a relatively minor problem when it is first discovered. But the water can cause much more damage than the plumbing problem itself.

Water can get under flooring, behind walls, under and behind cabinets, and into other parts of the home. Depending on how the loss happened and the terms of your homeowners insurance policy, the resulting damage may be covered by insurance.

If you have a water damage claim involving hidden plumbing leaks, damaged cabinets or flooring, mold, or an insurance company that denied or underpaid the claim, contact Schatzman & Hovanyecz, P.A. so we can review the loss and the applicable policy.

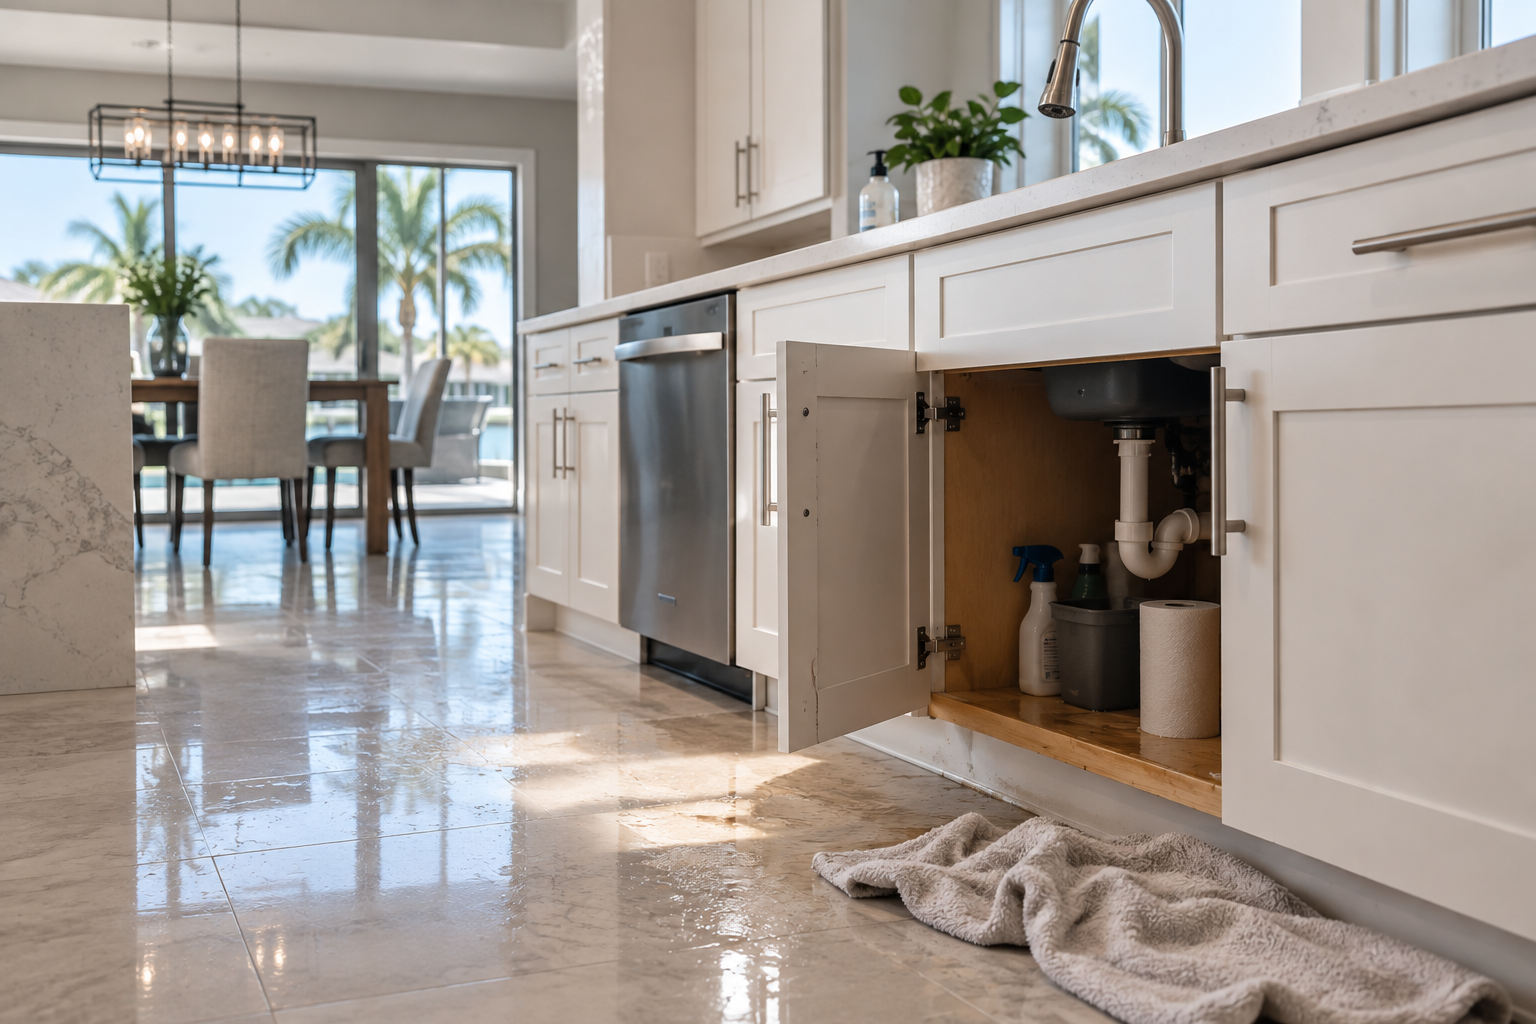
Water leak in a modern Florida kitchen affecting cabinets and tile flooring

Common Water Damage Claims

Common water losses include leaking or broken pipes, failed plumbing supply lines, refrigerators and ice makers, washing machines, dishwashers, water heaters, toilets, showers, air-conditioning systems, drain lines, and roof-related water intrusion.

A failed supply line, for example, may be inexpensive to replace, but the leak may damage cabinets, flooring, drywall and other parts of the home. Getting to the broken plumbing can also require removing drywall, tile, flooring, cabinets, or even part of a concrete slab. Depending on the policy and cause of the loss, the cost of accessing the broken plumbing and repairing the resulting damage may be covered even when the cost of replacing the failed plumbing itself is treated differently.

Older homes can also experience water losses involving broken or deteriorated drain lines, backups and overflows.

Hidden or Unknown Plumbing Leaks and Mold

Not all plumbing leaks are immediately visible. A pipe can leak inside a wall, under flooring, or behind cabinets for some time before the homeowner has any reason to know there is a problem.

Different insurance policies treat hidden or ongoing leaks differently, so the specific policy language and when the leak could reasonably have been discovered can be important.

Moisture may also remain behind walls, under flooring, or behind cabinets even after visible water has been cleaned up, and that moisture can lead to mold.

Although homeowners sometimes refer to a separate “mold claim,” the important question is usually what caused the water or moisture that led to the mold. Mold found behind cabinets or walls after a covered water leak may be part of the overall loss, although homeowners policies often contain separate provisions and limits for mold-related damage and remediation.

Condominium owners can face an additional problem when the water comes from another unit or from another part of the condominium building.

What Should You Do After Discovering Water Damage?

Take reasonable steps to stop the leak and prevent further damage, but also document what happened before the evidence disappears.

Take photographs and videos of the water, the source of the leak if it is visible, and the areas that appear damaged. If a plumber identifies what failed, ask the plumber to document it and preserve the damaged plumbing part when possible.

Do not assume that cleaning up the visible water means all of the damage has been found.

Damage to Cabinets and Flooring

Cabinets and flooring are often some of the most expensive parts of a water damage claim.

Water can get underneath and behind kitchen or bathroom cabinets, damaging the bottom, back, shelving and other parts of the cabinets that may not be visible from the outside. Moisture trapped behind or underneath cabinets can also lead to mold.

Replacing damaged cabinets may affect countertops, backsplashes and other cabinets that were installed together.

Flooring can create similar problems. Water can travel underneath wood, laminate, vinyl or tile flooring and spread beyond the area where the leak was first found. The damage may therefore be larger than what is visible during the first inspection.

What If You Cannot Stay in the Home?

Some water losses make it difficult or impossible to remain in the home while remediation and repairs are being completed.

Mold remediation may require part of the home to be sealed off, plumbing work may temporarily leave the home without running water, or major repairs to a kitchen, bathroom or flooring may make normal use of the home difficult.

Many homeowners policies include Additional Living Expense, or ALE, coverage when a covered loss makes the home unfit to live in. Depending on the policy and circumstances, ALE may help with the increased cost of temporarily living somewhere else while repairs are completed.

When the Insurance Company Does Not Pay Enough or Denies the Claim

Even when an insurance company accepts a water damage claim, there may be disagreement about what was damaged and what it will cost to properly repair the home.

That can be especially important when the claim involves cabinets, flooring, the cost of accessing broken plumbing, mold remediation, or damage that was not visible during the initial inspection.

Insurance companies also deny water damage claims for a variety of reasons, including disputes over what caused the loss, how long the leak existed, whether an exclusion applies, or whether the policyholder complied with policy requirements.

A denial does not necessarily mean the insurance company’s decision is correct. Water damage claims often turn on the specific facts of the loss and the language of the policy.

At Schatzman & Hovanyecz, P.A., we represent Florida homeowners and condominium owners in disputes involving plumbing leaks, water damage and resulting damage to their property. If your insurance company has denied your claim, failed to fully pay it, or you simply have questions about your water loss, contact Schatzman & Hovanyecz, P.A. to discuss your claim.

Was Your Florida Termite Damage Insurance Claim Denied?

Homeowners are often told that termite damage is not covered by homeowners insurance. When an insurance company denies a claim based on termites, insects, deterioration, or maintenance, many homeowners assume there is nothing more they can do.

That may not always be the case. A termite-related denial can sometimes be challenged, particularly when hidden termite damage causes a sudden failure, downward movement, or collapse of part of a home and the homeowner had no knowledge of the ongoing infestation or damage.

If your insurance company denied a claim involving hidden termite damage, a ceiling that dropped or deflected downward, or another possible collapse, contact our office before assuming the denial is final.

Schatzman & Hovanyecz, P.A. has successfully challenged termite-related insurance denials. Every claim is different, and whether a denial can be overcome depends on the particular facts, the available evidence, and the homeowner’s insurance policy.

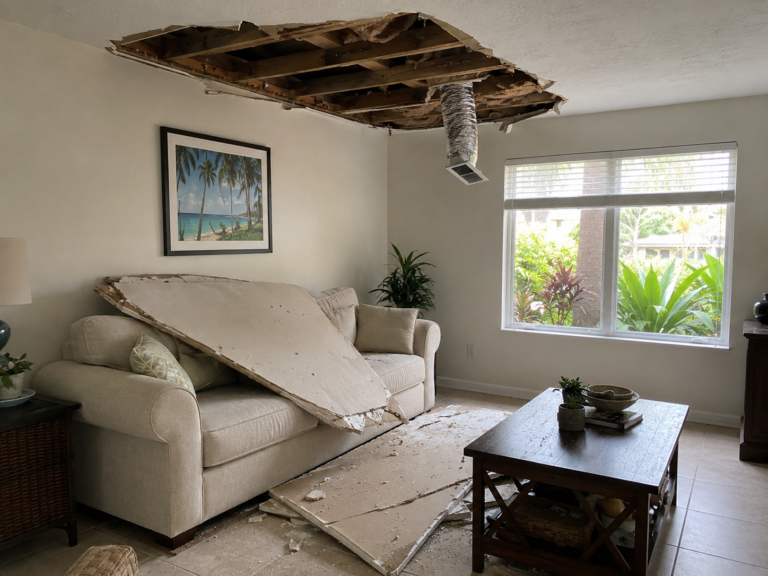
Partial ceiling collapse with fallen drywall in a Florida home

Why Are Termite Claims Often Denied?

Insurance companies frequently deny termite claims by characterizing the damage as the result of an ongoing infestation, deterioration, or a maintenance problem. A denial letter may state that termites were present for a long time or that the homeowner should have discovered and addressed the condition earlier.

But termites can damage areas that are completely concealed from the homeowner. They may be above a ceiling, behind a wall, beneath flooring, or inside structural wood. A homeowner may have no visible warning that serious damage is developing.

If your insurer has denied a claim on the ground that the termite activity must have been ongoing or should have been known, we can review the denial and the circumstances surrounding the loss.

Hidden Termite Damage and a Possible Collapse

A claim may require closer examination when termite damage remains hidden until part of the home suddenly fails, drops, deflects downward, or caves in. A common example is a ceiling that suddenly moves downward or partially gives way and exposes termite damage in the concealed wood above it.

A collapse does not necessarily mean that an entire ceiling, roof, or building must fall completely to the floor or ground. Depending on the event and the policy, a sudden downward deflection or partial caving in of building materials may warrant evaluation as a possible collapse even though the structure remains standing.

Homeowners should not try to decide from the appearance of the damage alone whether an event technically qualifies as a collapse. If a ceiling, roof component, floor, or other part of the home suddenly moved downward or lost support, contact our office so we can evaluate the event and the applicable policy.

It may also matter whether the homeowner knew about the infestation or damage before the event. A homeowner who had no visible signs and no knowledge of the concealed condition may be in a different position from someone who was aware of active termite damage and allowed it to continue.

A Ceiling Does Not Have to Fall Completely

Many termite-related claims involve a ceiling because termite damage can remain concealed in the wood above the living space. Sometimes drywall falls to the floor. In other situations, the ceiling or supporting materials may suddenly drop, sag substantially, or deflect downward without completely detaching.

Do not assume there is no potential claim simply because the ceiling did not fall all the way down. The nature and extent of the movement, whether it occurred suddenly, the condition of the concealed materials, and the wording of the policy should be reviewed before deciding whether the event may qualify as a collapse.

Our firm can examine what occurred, what the homeowner knew before the loss, why the insurer denied the claim, and whether there is a basis to challenge the decision.

What Should You Do After a Sudden Termite-Related Failure?

If a ceiling or another part of the home suddenly falls, caves in, or moves downward, photograph and record the condition before cleanup or repairs when reasonably possible. Keep fallen materials and damaged wood when possible, and save inspection reports, termite records, correspondence, and photographs provided by the insurance company.

You should also keep the complete denial letter and request a copy of the insurance policy that was in effect when the event occurred. These materials can help us evaluate the claim.

Avoid assuming that the presence of termites automatically ends the insurance inquiry. The nature of the event, whether the damage was hidden, what the homeowner knew, and the insurer’s stated reasons for denial may all be important.

Has Your Termite or Collapse Claim Been Denied?

An insurance company’s denial is not necessarily the final answer. We have successfully challenged termite-related denials, but each claim must be evaluated individually.

If your homeowners insurance company denied a claim involving hidden termite damage, a ceiling that fell or moved downward, or another possible structural collapse, contact Schatzman & Hovanyecz, P.A. We can determine whether the event may qualify as a collapse and whether there may be a basis to challenge the denial.

Hurricane Irma

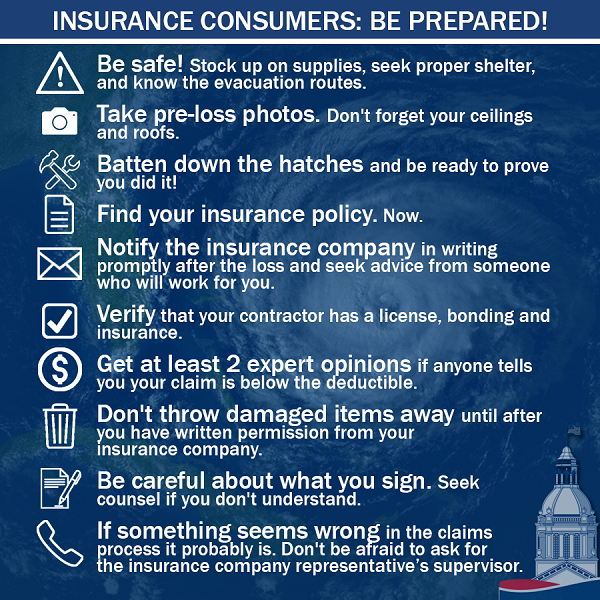
As we all prepare for Hurricane Irma, and after you have made sure you and your family are safe, it is important to take some quick steps to ensure that once Hurricane Irma passes, any hurricane related damage to your home or business is promptly reported to your insurance company, assessed, inspected by your insurer and other professionals, repaired by a reputable contractor, and ultimately paid for in full by your insurance company (less your deductible of course).

The Florida Justice Association has put together a great list of tips you should keep in mind to ensure everything with your insurance company goes smoothly after the storm. Keep in mind that immediately after the hurricane, there will be people out here looking to take advantage of our desperate citizens. Hurricane Irma Preparation This is why one of the most important post-storm tips is to know exactly who you are dealing with and what you are signing before you enter into any agreements with anyone. Be careful of anyone who tells you not to worry about the cost of their services because your insurance company will pay for it. The bottom line is: do not sign anything you are not 100% certain about without first consulting an attorney familiar with the handling of property insurance claims.
We hope that insurance companies will be quick, fair, and reasonable in adjusting Hurricane Irma claims, but there will inevitably be issues. We will be here after Hurricane Irma to provide legal advice and representation to our fellow Floridians affected by the storm and dealing with their insurance companies. We hope that the storm’s impact is minimal, but property damage is almost a certainty and you should ensure your property interests are protected, both before and after the Hurricane Irma.

Your Property Damage, Our Problem!

Understanding Your Deductible Under a Homeowners Insurance Policy in Florida

All Florida homeowners insurance policies carry a deductible usually ranging from $500 to $2,500.  Just like an auto insurance policy, the deductible is the policyholder’s financial responsibility for a portion of the damages in the case of an insurance claim.  Unfortunately, deductibles have led to some confusion among policyholders deciding if they should file an insurance claim.

Occasionally, I hear concern from policyholders who tell me that they don’t want to file a homeowners insurance claim because they don’t have the money to pay their deductible or are concerned about having to come out of pocket for the deductible.  With a $2,500 deductible, it would be impossible for some families to meet this financial burden, especially when faced with potentially other costly repairs and damages to the their home stemming from the insurance claim.  However, it’s important for policyholders to understand that under a typical Florida homeowners insurance policy, you do not have to pay your deductible to the insurance company in the event of an insurance claim; the amount of your deductible is simply reduced from the total payment issued to you by the insurance company for the damages to your home.

For example, if you suffer a plumbing leak that causes $20,000 of damage to your home, and you have a $2,500 deductible, your insurance company would issue you payment in the amount of $17,500. You do not have to pay the insurance company your $2,500 deductible.  In fact, you do not have to come out of pocket at all as long as you can find someone to make complete repairs to your property with the amount of money paid by the insurance company.  Whether the insurance company paid enough to begin with is another issue previously discussed here.

There are however certain circumstances where the payment of your deductible can change.  Depending on your insurance company, you may have an insurance policy that provides the insurance company with the “right to repair” or “option to repair” your home as previously discussed in our blog post entitled “The Insurance Company’s Right to Repair and Option to Repair; What are Your Rights and Options?”  If your insurance company utilizes this process, rather than paying you directly for the damages to your home, the insurance company will choose and send their own contractor to make repairs to your home.  The insurance company then pays their chosen contractor directly for the cost of repairs.  In this situation, depending on your insurance company, you may be obligated to pay your deductible directly to the insurance company’s contractor before the work begins.

If you or anyone you know has questions about insurance policy deductibles, do not hesitate to contact us.

What Does Appraisal Mean in a Florida Homeowners Insurance Policy?

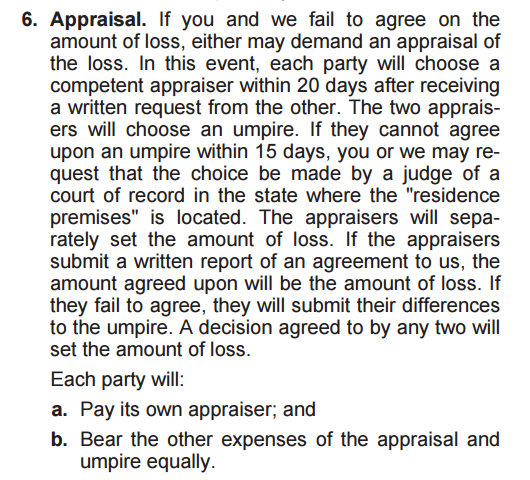
Many Florida homeowners insurance policies contain a specific clause called appraisal which can have a huge impact on the outcome of your homeowners insurance claim.  Most homeowners have no idea that an appraisal clause exists in their insurance policy and find out for the first time when their insurance company demands appraisal of their homeowner’s insurance claim.  To get an idea of what you are looking for, a typical appraisal clause looks similar to this: appraisal clause

These appraisal clauses are nearly identical between most Florida homeowners insurance policies and can be used by either the homeowner or insurance company to determine the total amount of damage to the home.  However, before a claim can be submitted to appraisal, the homeowner and insurance company must have a disagreement regarding the dollar amount of damage to the home.  For example, if the insurance company decides that a plumbing leak has caused $5,000 of damage to your home but your contractor gives you an estimate of $20,000 to make repairs, the insurance company is entitled to demand appraisal to determine what the insurance company is obligated to pay you for your damages.  Ultimately, this may result in you receiving less than the $20,000 it will cost you to make repair the damage.

The appraisal process requires that the homeowner and insurance company each select their own appraiser to represent them.  The appraisers will then try to come to a mutual agreement as to the damages to the home.  If they are able to agree, the final number will fall somewhere between the damages determined by your or your contractor and those determined by the insurance company.  If the appraisers cannot reach an agreement, the appraisers are required to select a neutral umpire who will then make the final determination as to the amount of damages.  The number arrived at via appraisal is FINAL and outside of very specific circumstances, cannot be challenged or circumvented.

Even in light of the nature of appraisal, is not necessarily a bad thing.  Given the right circumstances, appraisal can be a benefit to the policyholder.  In other circumstances, where appraisal may not be preferred, certain actions can be taken to avoid appraisal.  If you have any questions about appraisal or about your claim in general, please don’t hesitate to contact us.