Florida homeowners pay thousands of dollars in insurance premiums each year, trusting that their insurance company will be there to help them when their home is damaged. Unfortunately, Florida insurance companies sometimes incorrectly deny claims, leaving homeowners to fend for themselves and face significant repair costs without the coverage they expected.
Insurance companies may deny claims based on incorrect conclusions about what caused the damage, misinterpretations of the policy, or incomplete investigations. They may also rely on exclusions that do not actually apply to the damage.
Just because your insurance company denied your claim does not mean its decision was correct.
At Schatzman & Hovanyecz, P.A., we have successfully challenged denied homeowners insurance claims and obtained coverage for our clients. If your claim has been denied, we can help determine whether you may be entitled to payment.
Why Do Insurance Companies Wrongfully Deny Homeowners Claims?
Most Florida homeowners insurance policies provide what is known as all-risk coverage for damage to the home. This means that damage to the home is generally covered unless the insurance policy specifically excludes it. If the insurance company denies the claim, it generally has to prove that the damage is excluded under the policy.
This is an important protection for homeowners. Insurance companies cannot simply deny claims by pointing to an exclusion. They must prove that the exclusion applies to the reported damage or cause of loss.
Some of the most common reasons insurance companies give for denying claims, even when coverage may exist, include:
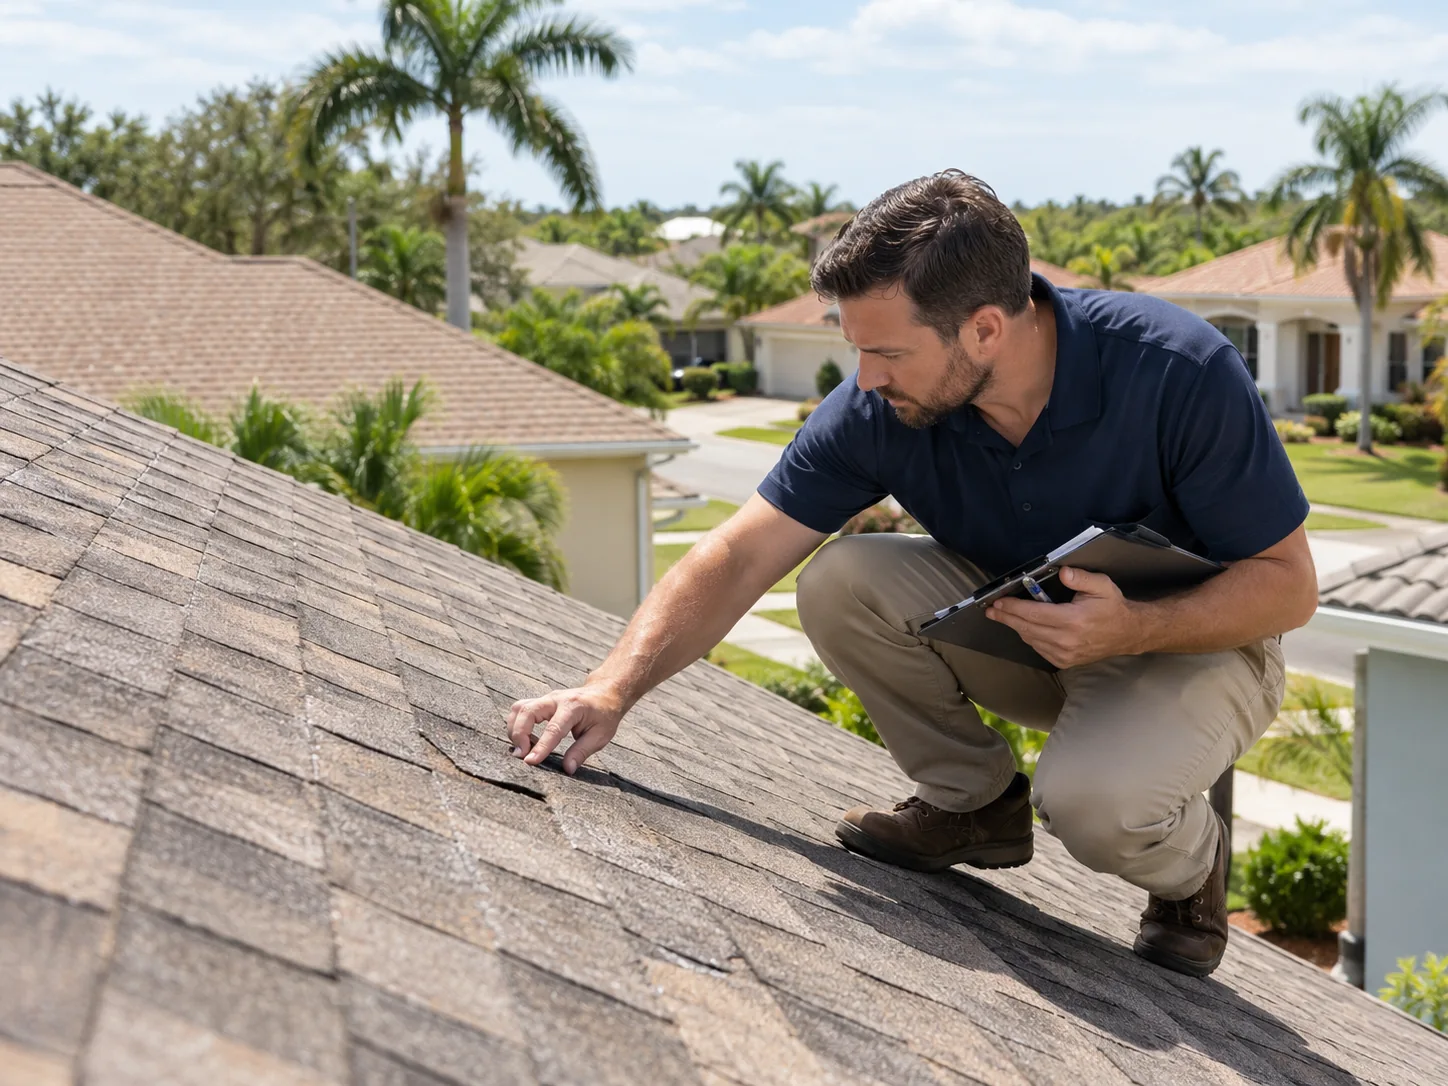
Roof damage blamed on age or wear and tear. Insurance companies frequently deny roof claims by attributing damage to the age of the roof, deterioration, or poor maintenance. However, an older roof can still suffer new damage during a hurricane or severe storm. The existence of prior wear and tear does not automatically mean that new storm damage is excluded from coverage.
Roof damage blamed on prior repairs. Insurance companies may also deny roof claims because the roof was previously repaired or contains patched areas. However, the existence of prior repairs does not automatically mean that new damage is excluded. A roof that has undergone repairs can still sustain new damage from wind or other covered events.
Water damage blamed on long-term leaks. Insurance companies may deny water damage claims because they believe a plumbing leak continued for a long period of time. However, leaks often occur behind walls, beneath flooring, or inside cabinets, where homeowners may not discover them immediately. A homeowner may not discover the leak until water stains, damaged flooring, or other signs of damage become visible. Depending on the policy and circumstances, the resulting water damage may be covered.
Damage blamed on faulty construction or maintenance. An insurer may attribute damage to defective workmanship, improper installation, or a lack of maintenance. Although policies often exclude these causes of damage, the resulting damage may still be covered.
Claims denied because of late reporting. Insurance companies may deny claims because they believe the homeowner waited too long to report the damage. However, the circumstances surrounding the delay and whether it affected the insurer’s ability to investigate may be important in determining whether the denial can be challenged.
Denials involving hidden damage. Some insurers deny claims involving damage that developed out of sight, including concealed water damage and structural deterioration. Yet some insurance policies provide coverage for specific types of resulting damage.
For example, certain policies cover a qualifying collapse caused by hidden termite damage, even though termite damage itself is generally excluded.
Our firm has successfully challenged denials involving hidden termite damage and hidden water damage. Learn more in our article on denied termite damage insurance claims.
You can also read our article on Florida water damage insurance claims for additional information about plumbing leaks and related coverage disputes.
An insurance company’s stated reason for denying a claim does not necessarily justify the denial.
Can a Denied Homeowners Insurance Claim Be Overturned?
Yes. A denied homeowners insurance claim can be overturned, and our firm has successfully obtained insurance coverage for clients whose claims were initially denied.
Some denials are reversed through negotiations or mediation, while others require legal action. A denial letter does not necessarily prevent you from recovering insurance benefits.
At Schatzman & Hovanyecz, P.A., we have experience challenging denials involving hurricane damage, plumbing leaks, policy exclusions, and other disputed losses.
If your claim was denied because of the condition of your roof, prior roof repairs, a plumbing leak, hidden damage, or another disputed issue, our firm may be able to help you obtain the coverage you are entitled to under your insurance policy.
What Should You Do After Your Insurance Claim Is Denied?
If your homeowners insurance claim has been denied, keep the insurance company’s denial letter, take photographs of the damage, and keep any estimates or inspection reports you have received.
It is important not to delay. Florida insurance claims are subject to deadlines, and waiting too long may affect your ability to pursue coverage.
Having an experienced property insurance attorney review your denied claim can help you determine whether the denial should be challenged.
Florida Homeowners Insurance Claim Denied?
At Schatzman & Hovanyecz, P.A., we have successfully overturned insurance claim denials and obtained benefits for homeowners throughout Florida.
If your insurance company has denied your claim, you may still be entitled to payment for your property damage. You do not have to accept the insurance company’s decision without having it reviewed.
Contact our firm today for a free consultation. We can review your denied claim and help you determine whether you can recover the insurance benefits you were denied.